Research & Insights — Secondary Advisory, Market Reports

Lazard 2024 Secondary Market Report

January 23, 2025

Collage of city skylines

Share

Lazard PCA Becomes Lazard CL logo

Research Archive Disclaimer

The research and related materials in this archive were produced prior to the formation of Lazard CL. They reflect the views, data, methodologies and market perspectives of that firm as at their respective dates of publication, and have not been updated, restated or reconciled following the formation of Lazard CL. Nothing in this archive should be taken to represent the current views of Lazard CL, and it is provided for historical and informational purposes only.

Secondary Market Surges to Record $152 Billion Amid Shifting Exit Strategies and Rising Capital Influx

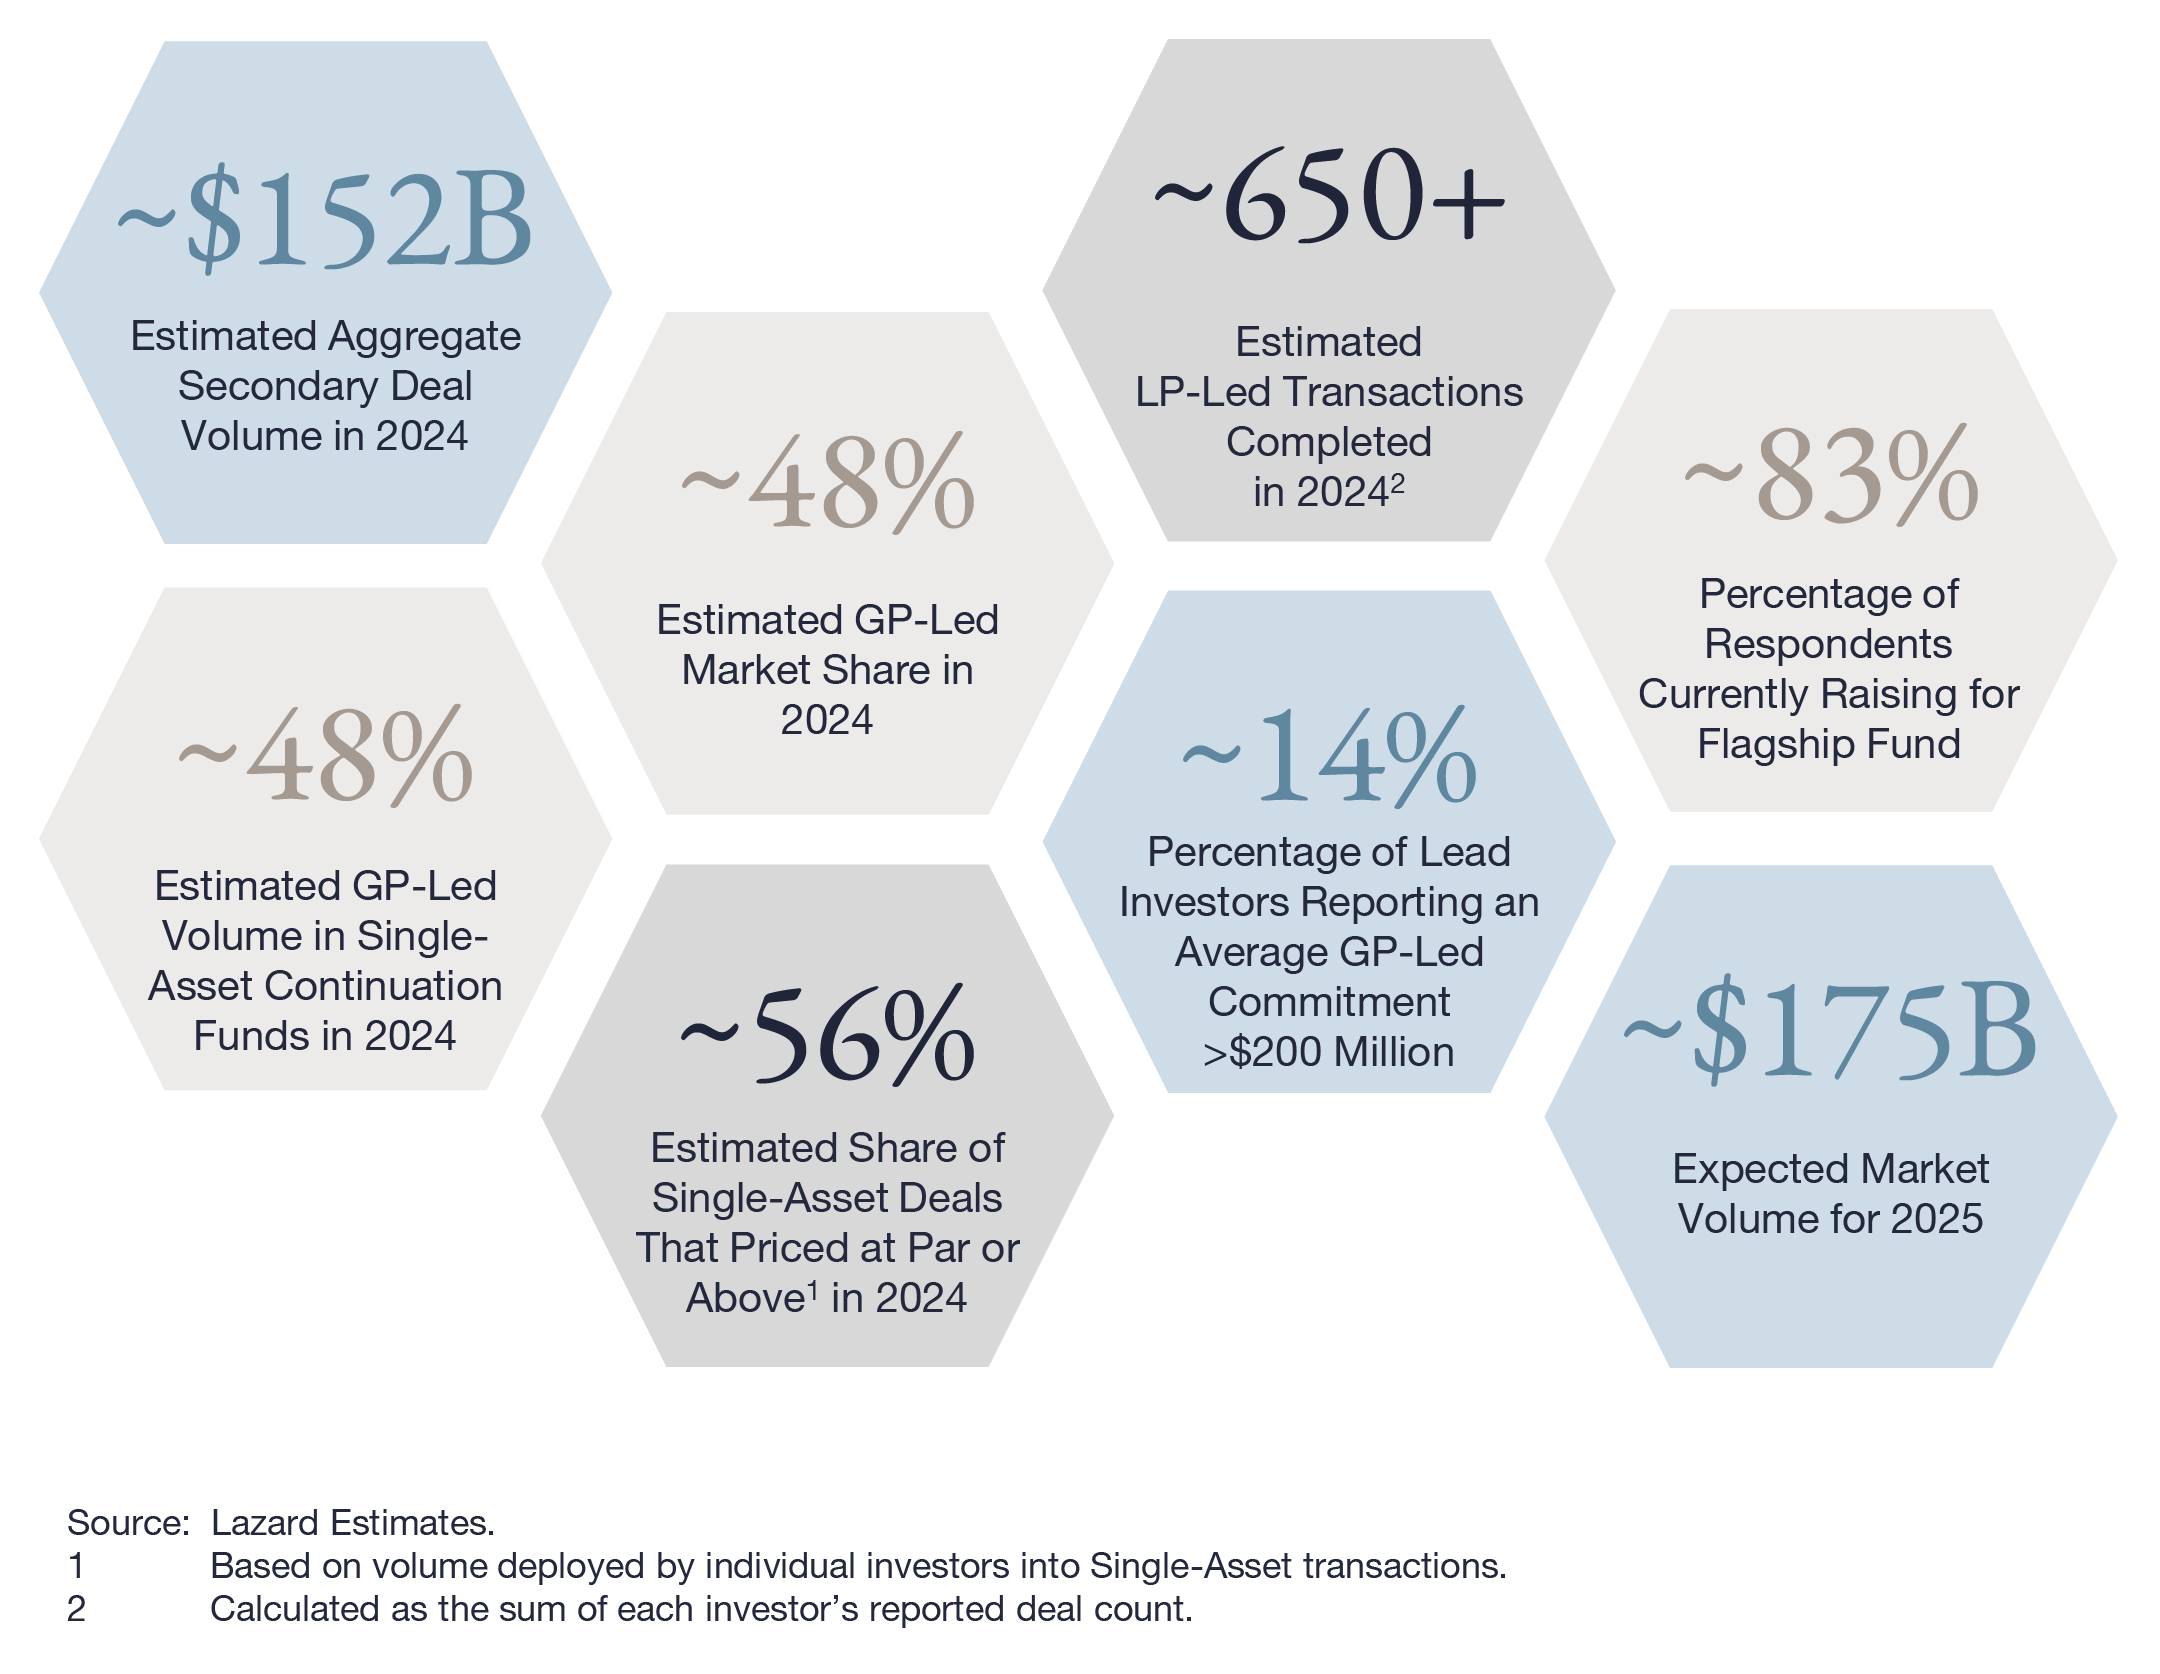
This year, the secondary market hit a record $152 billion in volume, surpassing the previous high set in 2021. Despite positive trends in M&A and IPO markets, limitations on these exits pushed sponsors and limited partners toward GP-led and LP-led secondary markets. New buy-side entrants, rising '40 Act fund AUM, and successful secondary fundraising have increased available capital and driven up pricing. While traditional exit markets are expected to improve next year, sponsors and limited partners are likely to remain active in the secondary market in 2025.

Chart with 2024 market stats

Our Key Findings:

  • The GP-led market in 2024 generated $72 billion, building on early-year strength, with Single-Asset Continuation Funds surging in popularity for "trophy" asset deals.

  • GP-led pricing improved across deal types, with secondary investors deploying larger check sizes compared to prior years. North America remained the largest market, normalizing volumes after an active first half in Europe.

  • The LP-led market continued to grow as strengthened pricing and high liquidity demand persisted. Improved visibility into near-term liquidity events significantly boosted Buyout pricing.

  • Notable improvements in appetite for Growth and Venture Capital were driven by dedicated capital pools, with rising ’40 Act fund inflows fueling competition and higher pricing for diversified portfolios.

  • Capital formation in the secondary market is growing steadily, with several large managers expected to hold closings for flagship and specialized funds in 2025.

  • Secondary managers who held large final closings earlier in 2024 are preparing to reenter the market, with many planning to fundraise next year.

  • Success in fundraising for sub-strategies (e.g., Private Credit, Infrastructure, and Venture Capital secondaries) and new entrants will inject more capital into the market, setting the stage for continued growth.
The Latest Research & Insights from Lazard CL

image of the Singapore skyline at dusk
October 12, 2026 Research & Insights

Campbell Lutyens Asia-Pacific Private Markets Report 2026

Collage of city skylines
August 13, 2026 Research & Insights

Lazard Interim 2026 Secondary Market Report

Duotone image of modern building
August 13, 2026 Research & Insights

Campbell Lutyens Secondary Market Report 1H 2026

View all